除了估值受压,辉达亦面临毛利率下滑与竞争加剧的挑战。由于记忆体等关键零组件成本走高,其毛利率预计将在第四季下滑至72%以下;与此同时,包括Meta与Alphabet在内的主要客户正积极研发自家AI晶片,市场对辉达长期市场地位动摇及获利能力萎缩的担忧因而加剧。
尽管市场对资料中心建置及AI资本支出前景抱有疑虑,执行长黄仁勋仍称辉达为「成长型价值股」并强调其价值被严重低估。部分市场分析师亦认为,除非大型云端业者大幅缩减开支或面临严苛法规,否则AI基础设施投资不易放缓,当前历史低档的估值倍数可能为投资人提供了具吸引力的进场机会。
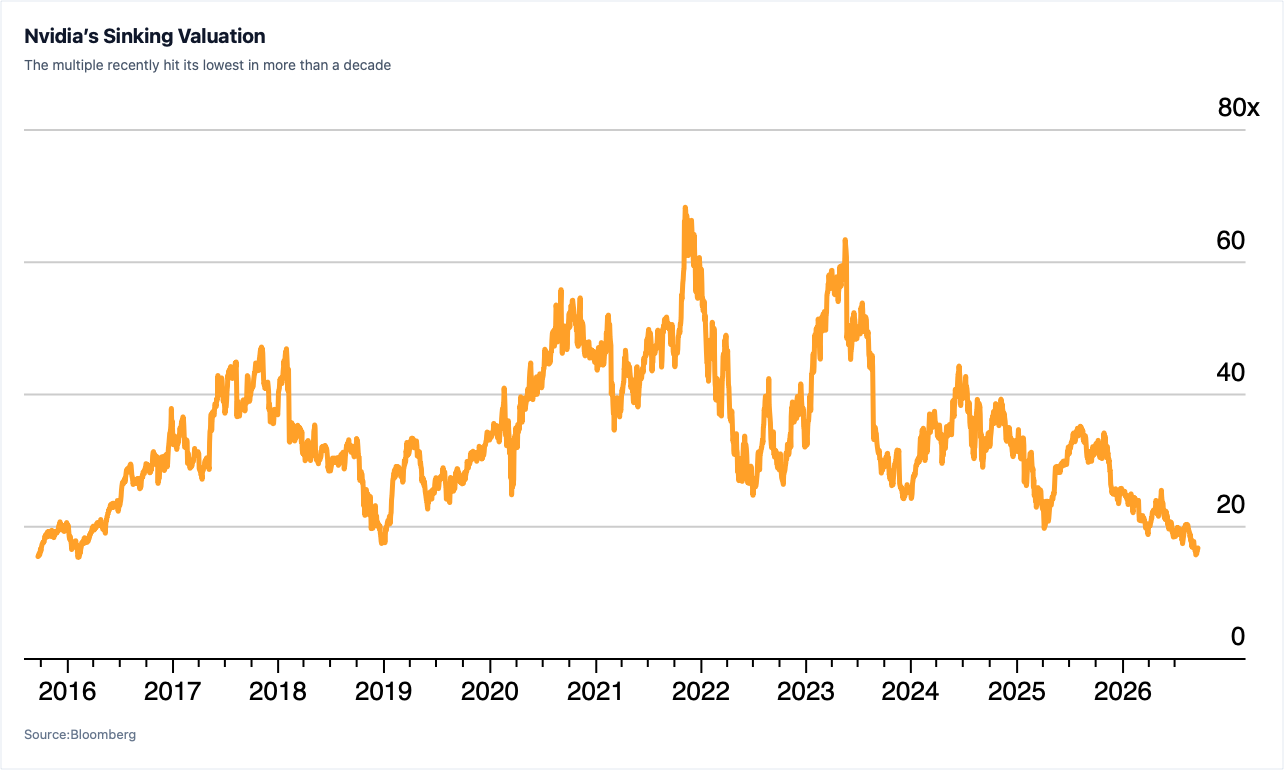
Nvidia Corp.'s sinking stock valuation is flashing a warning sign regarding the sustainability of its explosive profit growth. The company's forward price-to-earnings ratio has dropped below 17 times, marking its cheapest level in over a decade, indicating widespread market skepticism despite consensus projections of a 90% revenue increase and 99% net income surge for fiscal 2027.
Beyond valuation compression, Nvidia is confronting narrowing gross margins and mounting industry competition. Rising component expenses such as memory chips are projected to press fourth-quarter margins below 72%, while top customers like Meta Platforms and Alphabet expand in-house chip development, stirring investor worries over weakened pricing power and market share erosion.
Although lingering concerns persist over potential slowdowns in AI infrastructure spending, CEO Jensen Huang insists the company is an undervalued 'growth value stock.' Some market strategists maintain that without drastic cloud capital expenditure reductions or crippling regulatory hurdles, the discounted multiple presents an attractive risk-reward entry point for investors.